House Mountain Partners

The Resource Shift - A Play in Three Acts

Chris BerryComment

Click here for a PDF copy of the Introduction and Act I, Pillar I.

Click here for a PDF copy of Act I, Pillar II on Demographics.

What follows is a series of essays I am writing where I lay out my thinking on what has happened in the global economy in the last quarter century, what forces are/were responsible for this change, what the future may look like, and the implications for investment in critical materials. The model that defined much of the past 25 years, specifically low cost of capital globalization, optimized supply chains, and globally integrated trade is moving towards a model shaped by global fragmentation, the combining of econoimic and national security, economic chokepoints, and competition for strategic materials.

This shift has implications for capital allocation and investment returns, specificallt for critical materials.

The story is broken down into three Acts much like a Shakespearean play. This is an apt comparison given the triumph and tragedy we have seen and are likely to continue to experience as a host of forces collide to both create and destroy opportunities across borders.

Act I discusses the global macroeconomic forces that led to change and makes the case that these are in many ways irreversible; Act II discusses constraints to growth in this new order, and Act III discusses the implications of these changes for investors.

The economic assumptions many of us grew up on can no longer be taken for granted. Critical raw materials still form the backbone of economic growth, but these assets and projects are set to take on an elevated level of importance as governments prioritize security and resilience. The chase for the lowest cost of production is over. The “game” for investors will be figuring out which projects can be financed and operated profitably given these emerging economic and geopolitical constraints.

Each of the essays serves as a pillar which supports this new economic operating environment. This document is also a work in progress, so comments are welcome.

ACT I – FORCES – When and Why the World Changed

Pillar 1: The End of the Old Order

It’s difficult to point to a single event that has altered the course of history and brought us to where we are today – increasingly fragmented trade, aging populations, relentless technological advances, and a political class that is increasingly disconnected from the “man on the street”.

I was born in 1974 and for the almost entirety of my life, the United States has been the trusted global hegemon. Hallmarks of a hegemon include a reserve currency, deep and liquid capital markets, the rule of law, provider of a security umbrella, and patroller of the high seas. This is all designed to help global trade grow unabated.

That said, something has changed. The trust that the US had built with allies over decades has eroded. Investors, stakeholders, and even many policy makers are (quietly) questioning who is in charge and who sets the rules for the future. Can the US be trusted to provide the benefits to allies mentioned above? The rhetoric coming out of Washington DC would lead you to believe that the global operating environment is in many ways “every man for himself”. This is best demonstrated by the headlines about increased defense spending in parts of the world like the EU.  Defense spending in 2025 will total EUR 418B, a 20% increase over 2024.  

Multiple events have effectively shocked the old order, forcing all of us to find a new equilibrium. Seminal events including the 9/11 attacks, the 2008 Global Financial Crisis (GFC), BREXIT, the COVID pandemic and the response to it, the Trump presidencies, and the inexorable rise of China are the most obvious examples. This is not an exhaustive list, but after each event, it’s fair to say that the world looked much different after than before. Each event put a crack in the façade of a world order whose time was running out.

This old order was designed to provide economic growth and a security blanket based on the idea of free trade and a single country (the US) providing that security and underpinning the growth through reserve currency status, deep financial markets, the rule of law, economic opportunity onshore, and a power military. The result was a set of mutually self-reinforcing conditions: the US exported security and economic opportunity, consumers benefitted from lower costs and access to a wider array of goods and services. China, with a giant workforce and low labor cost, was the other side of this coin, exporting deflation.

Now, many of those forces have halted or are in reverse. The Trump Administration is (rightly) pushing other countries to spend more of their own capital on their own defense, tariffs and export restrictions are increasing the production cost of goods, the reindustrialization push in the US championed by both the Biden and Trump Administrations is highly capital intensive, countries are actively looking at US Dollar alternatives such as bitcoin, and China’s low cost growth model is on the ropes. These changes all point to a higher cost, more inflationary world going forward.  There is an optimistic case centered around the deflationary push of technology such as AI and this will be discussed in a subsequent piece.

Here’s the main takeaway: A structurally higher cost of capital is colliding headlong into a higher demand for the physical raw materials (lithium, copper, rare earths) needed for the next phase of global economic growth.

This old order rested on a handful of assumptions:

·      Low interest rates were a permanent feature of business. Globalization allowed for labor arbitrage and set the stage for just-in-time inventory management which allowed companies to optimize their financial performance. China’s admission into the WTO in 2001 was the matchstick, when combined with the fuel of economic activity that arguably caused the forest fire we are experiencing today: the global economy grew, but at the expense of a shrinking manufacturing base in the West.  As a result, China utterly dominates many global supply chains, especially those for critical minerals. Many thought that lower interest rates would continue into perpetuity thanks to the “virtues” of capitalism and an enormous labor pool in Asia helping to keep costs down, and goods affordable to the masses. Here’s a chart of the US Treasury Ten-Year bond:
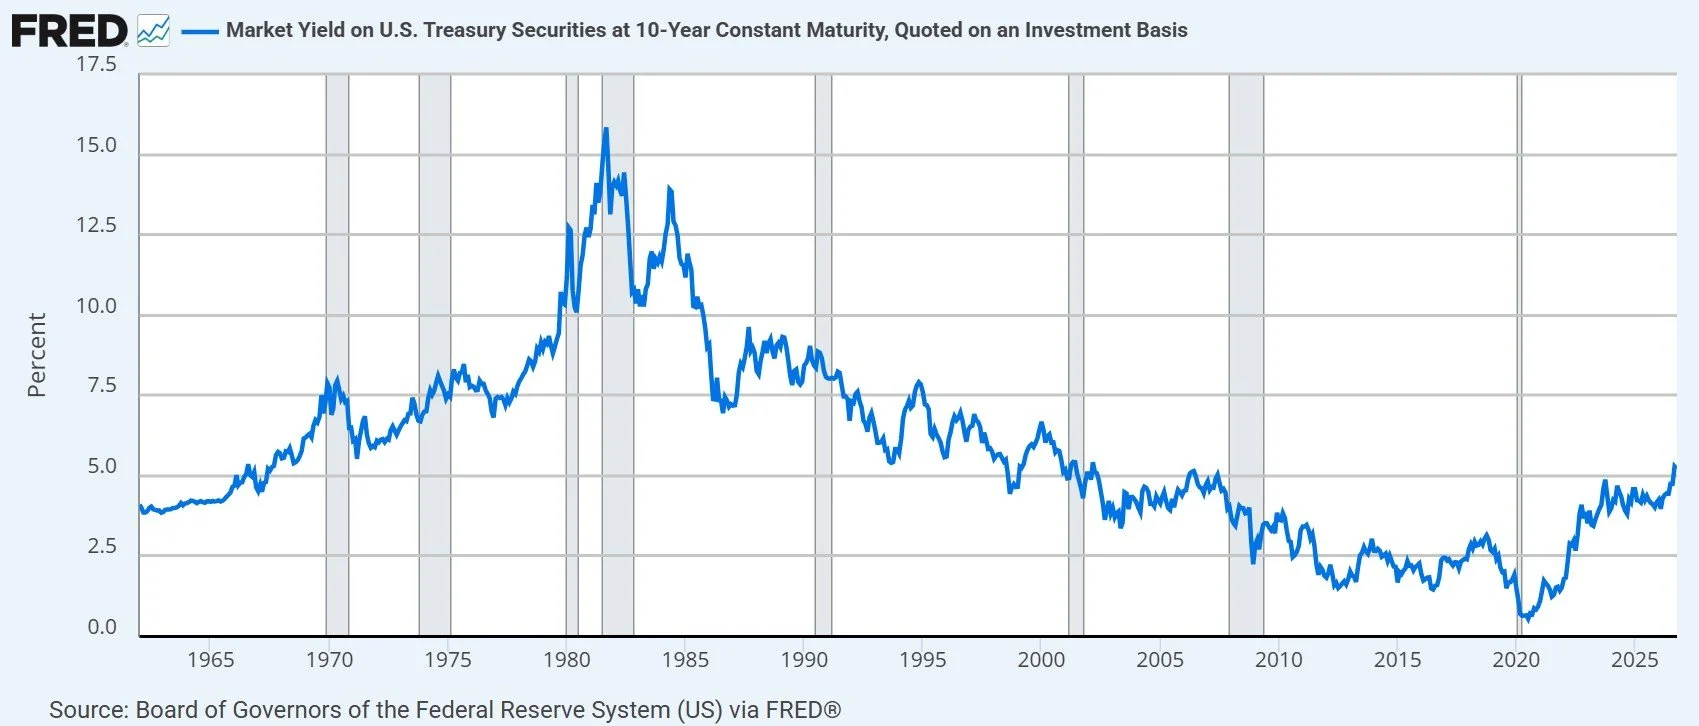
While this global benchmark is still low on a historical basis, the trend towards higher rates is undeniable.

·       The US would guarantee global security. The US military, dominant since the end of World War II and especially since the end of the Cold War, was the real force that ensured seas were patrolled, security blankets were sufficient, and economic growth globally would be the beneficiary. Democracy was also hoped to be a byproduct here, but has a much spottier track record. With the Trump Administration bullying allies into spending more on their own domestic defense, the US absence on the seas, in Europe, and elsewhere removes one of the strongest pillars of global economic growth in the last 80 years. Who (or what) fills that void remains to be seen.

·      Wide access to the US dollar. The US dollar has enjoyed the “exorbitant privilege” as the world’s reserve currency for decades and arguably still retains that designation despite competition from the Chinese Yuan, bitcoin, and other currencies. How much longer this privilege stays in place has been written about extensively and I won’t belabor it here. Countries wanted to and continue to hold US Treasury debt thanks to its perception as risk free. While the US has never defaulted on its debt (and I don’t think ever would), the largest economy in the world shouldering a $40 trillion debt burden where interest on the debt is now a larger budget line item than defense spending continues to give finance ministers indigestion. Everyone is looking for a US dollar alternative when none really exists. Additionally, the US dollar is now a tool of geopolitical leverage, through means such as sanctions and access to clearing networks like SWIFT. Iran, Russia, and other countries that run afoul of how the US thinks the world should run have found this out firsthand.

·      Just-In-Time inventory management took precedence over Just-In-Case, or supply chain efficiency took precedence over supply chain resilience. Capital allocation under a globalized trade network was designed to minimize costs, maximize profit, and grow at all costs. Perhaps no economic shock better exposed the fallacy of this thinking than COVID when the West woke up to the fact that one country, China, has spent the previous quarter century building supply chains to dominate multiple sectors of the global economy with plenty of excess capacity to boot. Supply chain restructuring is underway in the West, but it will be years before any significant fruit is borne.

It’s worth clearly stating that this Old Order was very, very good for financial assets such as stocks and those lucky enough to hold them and not so good for physical assets or labor. Low wages wasn’t an accident, but instead was the globalized economy working as designed. It was this design that set the stage for widening income inequality and the K-Shaped economy phenomenon.

The Three Breaks

The old order didn’t end at once but was exposed by at least three events, or breaks, that have brought us to where we are today.

The first break was really one of legitimacy – the GFC in 2008. While the mechanics of the global economic system did not end in 2008, the blind belief in them did. Phenomena like Occupy Wall Street and the fact that no Wall Street executives were held accountable for bringing the global economy to the verge of a depression were cases in point. Taxpayer-funded bailouts of banks largely responsible for this global economic calamity were the salt in the wound and set the stage for today’s K-shaped economy. The medicine for this heart attack – quantitative easing (QE) was terrific for financial asset prices while globalization kept a lid on wages. Income inequality was the result.

The second break was the COVID pandemic. While the response to the GFC was focused on saving the banks, the fiscal response to COVID was to put money directly into the pockets of consumers and businesses in an effort to maintain spending in a US economy dominated by the consumer. This laid the groundwork for the end of the low interest rate era as the flood of money into the US (and global) economy inflated goods prices and wages. One of the results is sticky inflation in the US that has been above target for over five years.

The third break isn’t a single event but is the willingness to weaponize sacred cows. Specifically the weaponization of the US dollar. While not a new phenomenon, the willingness of those in Washington DC to literally kneecap other economies by restricting access to US dollars has forced a rethink in Tehran, Moscow, and Pyongyang, but also raises eyebrows in friendly capitals. If the US is willing to use the dollar as a weapon against a country that doesn’t toe the line what would stop it from making and following through on similar threats to allies? There is a reason that gold and silver touched all-time highs recently and it isn’t your typical supply and demand argument.

There are, to be sure, other events or breaks which deserve a mention including Brexit, the wars in Ukraine and Iran, and both Trump Presidential elections. I would argue that the Trump elections are results of the breaks discussed above. The fallout from the GFC gave voters the impression that bad behavior on the part of “the elite” on Wall Street could go unpunished. After asset prices rebounded sharply thanks to the Greenspan/Bernanke Put, this distributional failure only cemented the idea that capital owners were above the law, and Donald Trump was the result – twice.

Sticky Inflation and the Rate Problem

 A big challenge for governments is balancing deficit reduction while undertaking massive spending plans to reindustrialize and reshore supply chains. Reindustrialization creates policy tension and needs loose monetary policy/low rates to succeed in that a lower cost of capital boosts investment returns. As mentioned, the COVID response was aimed at keeping the US consumer spending and the economy out of a recession. This was accomplished, but at a cost of higher domestic inflation as measured by the consumer price index. Industrial policy is inflationary (especially with the US economy at full employment). While the Department of War, for example, lends and grants hundreds of billions of dollars to kickstart critical material projects, the Federal Reserve must fight these inflationary activities by raising interest rates – raising the cost of capital for these capital-intensive projects. Do you see the problem? One arm of government is adding inflationary pressure by funding infrastructure, and another arm of government is trying to suppress inflation through monetary policy adjustments. Tighter money is self-defeating in that a long-lived mine or smelter is sensitive to interest rate movements in the way a software platform isn’t. The reindustrialization buildout in the US will only happen with these mechanisms (funding, price floors, etc) which, by their nature, are inflationary. The resulting policy mismatch is the result – governments wanting productive capacity for national security reasons, while the economics of a project (a lithium converter, for example) may not generate the required return needed to initiate the buildout. A higher cost of capital is the natural consequence of the need to reshore critical mineral supply chains. Oddly, an unfixable $40 trillion deficit doesn’t seem to be the biggest issue here. The issue is the true cost of capital in this new order. Increased demand for critical materials from defense and industry, higher input costs due to choked supply chains and wars, and resource nationalism all appear to substantiate my claim.

Consequences for Asset Owners

Obviously, these forces all imply significant investment implications. While the cyclical nature of critical materials isn’t going to change, how one invests must be re-evaluated given what I’ve laid out. Higher cost of capital is not as impactful for a brownfield mine or smelter but has significant implications for a greenfield project that is dependent on sustained robust pricing. Historically, capital was raised and allocated based on a project’s potential ability to generate cash and produce goods at a globally competitive cost. In the new order, security of supply, partnerships, and government support are now the sine qua non of Western critical material project selection.

This is why we have seen so much emphasis from Western governments on funding projects – the “China price” has been the number that drives returns. The country dominates so much of the supply chain from mine to market that a higher cost of capital only impedes capital allocation here implying low (or negative!) returns. If supply capacity doesn’t get funded and built in the current environment, no additional supply materializes in the future, and China still dominates. Subsidies are an unfortunate necessity.

With apologies to Adam Smith, the Invisible Hand is irrelevant in the new order and the sooner capital allocators accept this, the better. Subsidies such as price floors, off take agreements and grants and loans determine who builds projects and where they are built. Government support doesn’t necessarily fill a structural supply deficit but does allow Western producers to earn a return above the higher cost of capital. This essay and the ones that follow aren’t designed to pick winners – either via commodity or company – as they are all subject to these same challenges in the new order. Earning an “acceptable” return requires many of the same criteria as before (top tier management, high-quality asset, structural supply deficit, etc) but must accept government as a partner.

The Bear Case

With critical materials desperately needed in the West and governments fully behind this reshoring push, one would think that there is a “critical materials put” in place in the same way many investors came to believe that the “Greenspan Put” was in place to protect equity markets from falling too far, too fast. Any investment thesis deserves an analysis of its inverse and critical materials is no exception.

One of the core arguments is that interest rates stay structurally higher, which raises the cost of capital and lowers returns on greenfield projects. While this appears to be true based on five years of CPI data, interest rates in the 1970s were much higher than today and preceded a 40-year bond bull market, so regime changes aren’t necessarily a given. Additionally, the impact of AI (to be discussed in a subsequent essay) could eventually deliver the promised productivity gains to the global economy, keeping a lid on rates and raising wages without stoking inflation.

Second, demographics (covered in the next essay) would seem to favor secular stagnation and lower rates in the future as major economies continue to slow their population growth though, as I’ll demonstrate, this is a debatable premise.

Third, China continues to manipulate and in some cases flood critical metals markets, depressing prices and contributing to oversupply, decimating Western mine and refinery economics.

Fourth, the bond vigilantes appear in the form of much higher government bond yields, forcing governments to prioritize budget deficit management over fiscal expansion to the detriment of the reindustrialization thesis.

Fifth, trying to fund and manage projects with twenty year lives against a four-year election cycle is difficult regardless of the macro backdrop. The possibility that a post-Trump presidential administration changes or undoes some of the policies in place does exist, however unlikely. Combatting Chinese dominance in critical metal supply chains seems to be one of the few bipartisan issues in Washington DC these days.

The next essays in Act I will dive deeper into why the world has changed. The next essay will look at the effects of demographics.

Act 1, Pillar 2: Demographics as a Demand Driver

The grand bargain that underpinned economic growth in the West is breaking. The promise was that if you worked hard, you could own a home, raise a family, lead a comfortable quality of life and retire and leave something to your heirs. This model rested, in part, on favorable demographics: a society continuing to grow both organically (more babies being born), an expanding labor force, and immigration.

We are now learning what happens when the demographic tailwind disappears and the grand bargain reverses.

 Demographics in most of the West (and China and Japan) has gone in reverse. The consequences are wide as demographics directly influences economic growth rates, labor availability, inflation, and even demand for critical materials.

A central tension is the result. Dependency ratios are rising, implying that the demographic dividend which underpins economic growth is in danger. An aging population can lower economic growth and consumption which can lead to lower prices and interest rates (classic deflation). On the other hand, a smaller labor pool means fewer workers which enhances worker bargaining power (classic inflation). To complicate matters slightly, more worker leverage can accelerate investment into automation, possibly reducing the need for human labor. An aging population doesn’t necessarily mean fewer workers in absolute terms but does introduce fiscal pressures (funding Medicare and Social Security) which have no easy or apparent remedies. Again, this is not a phenomenon unique to one country.

For investors, the second point is important. If fewer workers are needed to support the economy, productivity gains are essential. While automation is one solution, this requires copious amounts of capital, new infrastructure, and raw materials – typically critical raw materials. Critical materials underpin this automation and so access to them is not optional.

The Rate of Change

To start, what is important to remember is that the age level isn’t the most critical piece of data, but instead the rate of change of age. In other words, how quickly or slowly is a society aging? While the charts linked here and in the Appendix show relatively uniform aging across many societies, it is China that is notable. With the working age population shrinking, this undercuts one of the country’s competitive advantages, namely it’s deep well of labor. So as China’s labor pool shrinks, the single most powerful reason for low-cost goods in the West (offshoring and labor arbitrage) looks to be ending. While moving manufacturing operations to other low-cost destinations such as Vietnam is a possible solution, no country can match China’s scale.

This introduces a fascinating debate around what happens on a macro scale when powerful inflationary forces (such as decreasing labor availability) crash headlong into powerful deflationary forces (such as automation). Overall, the deflationary case vis-à-vis demographics is currently the most widely believed. With an older population altering consumption patterns, this can keep a lid on inflation as lower consumption leads to lower demand, higher savings, and lower interest rates. Japanese economic performance in recent decades is an example.

The inflationary case is more interesting as it’s not as intuitive. The best primer on why inflation rather than deflation is the direction of travel was written by Charles Goodhart and Manoj Pradhan, titled ‘The Great Demographic Reversal’.  The central claim of the book is that the forces that led to decades of disinflation (China’s entry into the global economy and Baby Boomers in the workforce producing a labor glut) could have only happened once and is now in reverse as China ages and 10,000 Baby Boomers reach retirement age each day. It was this labor glut that kept inflation at bay and delivered the “goldilocks economy”.

The elderly then become consumers rather than producers and labor becomes scarce which enhances bargaining power, pushing up wages and fomenting inflation in the economy. Healthcare begins to account for a larger portion of the economy, is labor-intensive, and resistant to productivity gains. While I have always been in the deflation camp, I find this line of argument around inflation compelling and difficult to refute.

There is a deflation argument here with respect to aging societies and it rests with automation and technology. Those goods that can be manufactured by leveraging robotics hold the promise to counteract the possible inflationary forces unleashed by healthcare costs in an aging society. Which force “wins” is fodder for a robust long-term debate.

This is not a new phenomenon and historically when labor is scarce or expensive, capital comes to the rescue to build automation. Perhaps a positive takeaway for resource investors here is that automation is resource intensive. Enormous amounts of copper, lithium, rare earth magnets, and other materials are needed to bridge the gap between scarce labor and automation.  If labor remains scarce, capital must come to the rescue to automate activities that go unfilled.

So, the “flow” looks something like this:

Aging society –> labor scarcity –> automation –> materials and energy demand

Viewed through this lens, demographic changes look to be an accelerant to critical materials demand. It is important to remember that the economic forces behind inflation and the economic forces that determine demand for critical materials are not the same. While automation could be deflationary as it increases output at lower cost, significant investment is needed to build the infrastructure supporting automation which would be inflationary in the near-term. Investment demand, productivity, and substitution all impact this debate in different ways.


A Brief Note on Politics

Immigration is a force that can help defray the impact of an aging society, but its impact depends on how much immigration occurs and how quickly. Immigration in the US has been the rocket fuel for economic growth in the country for decades and so the current political climate around this issue is disheartening. Talk about cutting off your nose to spite your face. Without adequate immigration, labor availability remains in question, and the inflationary winds continue to blow.

The Bear Case

There are some reasons to be wary of the inflationary consequences of deteriorating demographics.

First, should automation and AI permeate through society faster than the labor pool shrinks, the aging threat could be deflationary after all as the much hoped-for productivity miracle arrives as promised. Stable economic growth underpinned by healthy wage growth and widespread access to transformational technology is a policymaker’s dream scenario.

 Second, there isn’t a good case study of an aging society producing inflation that I could find. Japan has, by most accounts, failed to ignite any inflation in the domestic economy despite decades of trying.

Third, the politics of immigration could reverse course and increased flow of labor across borders keeps a lid on any inflationary impulses. How likely any (or all of these) are is up for a rigorous debate, but in the interest of a balanced look at outcomes, they each need to be considered and handicapped.

Fourth, there is a possibility that inflation and deflation co-exist. As mentioned earlier, automation can be deflationary in an economy over the long-term through increased productivity while the buildout of the infrastructure needed to support the automation is inflationary due to substantial investment in raw materials, etc.

Given that these essays all involve AI in some way, harnessing the oncoming freight train of this technology could be viewed as a necessity rather than a “nice to have”. If populations shrink and grow old, productivity growth is an important solution to growing an economy with less available labor. Thus, building AI infrastructure and harnessing the technology becomes vital to maintaining a viable standard of living. The thesis here on demography is compelling, but the true implications for critical materials demand will depend on the rate of change of aging as well as how quickly automation technologies are adopted.  

The next essay in this series will focus on the automation imperative.


One Step Forward in The Battery Supply Chain Race?

Chris BerryComment

Part II of Shining City on a Hill or Fading Giant

This essay is a follow up to a piece I wrote close to two years ago in 2023. At the time, the critical metals markets were bucking under their own hype-induced weight, as reality caught up with the trajectory of EV demand and battery raw materials pricing.

To say that a lot has happened in the intervening months is an understatement. This piece will cover the significant changes in investment narrative, supply chain development and its glacial pace in the West, and how the West can compete in next-generation technology development with a Chinese juggernaut that the Trump Administration seems keen to help through self-defeating policies.

In the original essay, I argue that the US is at a crossroads with respect to critical materials supply chain development. The Biden Administration was able to pass the Infrastructure Investment and Jobs Act and the Inflation Reduction Act (the IIJA and IRA) which, over time, would offer a legitimate chance to build next-generation infrastructure to help US economic growth, productivity, and competitiveness. The table was seemingly set thanks to Biden’s progressive industrialization policies. Decoupling from China, started under Trump 1.0 turned out to be much harder to accomplish than first thought. Would a divided electorate rise to the occasion and set the pace for domestic industrial capacity growth to compete with a significantly advanced China? Unfortunately, these policies, along with COVID recovery funds, helped to foment significant inflationary forces in the US economy.

This, coupled with doubts around President Biden’s cognitive abilities, helped to usher Donald Trump back into the White House for Round 2 as POTUS. The answer to the question in my original piece – would the US remain the shining city on a hill – would have to wait.  

BETTER LATE THAN NEVER

That said, all was not, and is not, lost. Investors spent much of 2024 up until Trump’s second Inauguration debating one question: Was he serious? Was Trump serious about dismantling the IRA or was this bluffing? What about the tariffs? Rhetoric or reality? With a majority of investment and jobs created located in red states and hundreds of billions of dollars of capital already committed or sunk, there’s no way Trump would harm his base, right?

The answer to this question came in the One Big Beautiful Bill (OBBB) Act which significantly neutered the demand side signals in the IRA such as the 30D $7,500 USD consumer tax credit in favor of more supply side signals such as accelerated depreciation. Fortunately, section 45X in the IRA was preserved as it is enormously economically beneficial to those companies that can take advantage of the 10% production tax credit or the $45/KWh production tax credit on the battery module level.

If the change in subsidies weren’t bad enough for supply chain economics, the downward spiral in various metals prices is the ultimate insult to add to rather serious injury. The peak to trough moves in lithium, cobalt, and nickel should be painfully familiar to readers. Despite a recent rally in lithium prices which looks to be a head fake, a significant portion of the cost curve remains profoundly uneconomic.  Copper, the lone star performer, went on a spectacular run which was recently rug pulled thanks to the erratic tariff policy and implementation on the part of the Trump Administration. Higher prices will come, but how can upstream battery supply chain players manage their balance sheets in such an environment until halcyon days return?

Tariffs and the sledgehammer approach in their implementation are the biggest headwind to the buildout of any domestic industrial capacity. Any CEO I have spoken with in the past 8 months wants to know what, if any, tariffs they’ll have to deal with. This one-time shock to the company cost base is increasingly looked at as a cost of doing business in Trump’s Economy. In a perverse way, the tariffs intensify a new economic Darwinism where winners and losers are determined in the political arena and not in the free market. The dismissal of Adam Smith’s Invisible Hand in the current global trading system is a topic I examine further down in this essay. Not to be overlooked are the impacts of investigations such as Section 232, 301, Countervailing Duty Investigations (CVD), and other means under the guise of national security and unfair trade practices such as dumping. The recent completion of the CVD investigation on the part of the Department of Commerce targeting the Chinese dumping of anode materials in the US below cost and the finding weren’t at all surprising. What was a surprise to many was the realization that the roughly 160% tariff possibly slapped on Chinese anode material will sadly increase the cost of a lithium-ion battery in the US by as much as $7 per KWh. Benchmark Mineral Intelligence states that Chinese active anode material (AAM) was priced at $3,700 per tonne imported into the US. With these new tariffs, this import price increases to $9,300 per tonne. CITE. Though the anode is only roughly 12% of the cost of a lithium-ion battery, it’s clear that battery economics can be materially altered through tariffs on other metals and materials.

More distressing is the recent raid by US Immigration and Customs Enforcement (ICE) on a battery plant under construction by South Korea-based Hyundai and Japan-based LG. The raid, unannounced, resulted in hundreds of arrests due to visa issues which, at the time of publishing this essay, were still unclear. A development like this could do more long-term damage to making the US a favorable and welcoming investment destination. It’s a sad day. There doesn’t seem to be any differentiation between friend and foe regarding immigration in the US.

 A wholesale rejection of China-sourced battery materials, while a worthy (and achievable) goal, isn’t realistic at this point.  Tariffs applied broadly throw sand in the gears of any trading system and the recent immigration crackdown is perhaps a more ominous sign – hurting both economic competitiveness and alienating America’s allies. The tariffs and anti-dumping investigations are designed to hurt China, so it’s worth examining the evolution of China’s strategy and response to the Trump Administration’s approach.

CATCH ME IF YOU CAN

The Chinese investment model of state-directed Capitalism under President Xi is firmly in control but is changing. Moving “up the value chain” and away from less productive sectors of the economy such as low-value intermediate goods or real estate is the path forward. There is plenty of evidence to support this claim including platforms such as Made in China 2025. The plan targets strategic industries including aerospace, mobility, and energy storage. This level of focus is notable in that it also informs how Xi has chosen to respond to the Trump administration’s approach to tariff implementation. While Xi has responded to Trump’s tariffs initially in kind, much of the economic response from China is implemented with surgical precision. China has spent several decades building (excess) industrial capacity, this overbuilding has given the Chinese a unique advantage in the ability to process and produce a whole host of industrial and critical metals. While many here in the US have only recently woken up to this vulnerability, it has been well known in China, and this has been weaponized in the form of export controls. China has significant leverage here and won’t hesitate to use it.

Materials such as gallium, germanium, and graphite may become harder to access outside of China thanks to the need for permits granting access to the material. As the trade war between the US and China has dragged on, the Chinese menu of export restrictions has expanded to include technology such as lithium iron phosphate cathode (LFP) technology and culminating in the temporary halt of the exports of rare earth permanent magnets. It was this last salvo which brought the Trump Administration back to the table given the ubiquity and extreme importance of these materials in consumer electronics and, more importantly, national defense. This vulnerability cemented the $400M investment in MP Materials by the US Department of Defense (DoD). The deal includes a sizable equity stake in the company of 15% (plus a sweetener in the form of a warrant) for the DoD, a ten-year magnet off-take agreement, and a price floor for NdPr of $110/kg, well above the current market though this spread is narrowing. Banks including Goldman and JP Morgan will lend $1B USD and MP must contribute $600M in additional capital. This isn’t likely to be the last public/private investment partnership in critical sectors of the US economy. The price floor in this deal has the potential to completely reframe magnet economics ex-China (who controls 90% of the global market) which is perhaps the point. It’s unclear if MP would be able to build a non-China supply chain without it. Is this the only way companies based in the West can compete with China?

IF YOU CAN’T BEAT ’EM

I have often said that volatility along the strategic metals supply chain is a feature, and not a bug, of the new global trading system. If this is true, what is the best path forward as an investor or stakeholder? Some industries are too important to leave to the free market and it’s not bad to pursue and ensure domestic self-sufficiency, despite the cost. I think we can determine the industries (AI, batteries, etc.), but who decides and what the costs and tradeoffs are? A 15% equity stake in MP Materials makes sense as this is funded by the DoD through the Defense Production Act and is a show of skin in the game. Although that skin is funded by taxpayers who are on the hook for any loss here. What about the US Government taking a 10% stake in Intel? Or a 15% “tax” on NVIDIA chip sales to China? Which master do companies like Intel or NVIDIA serve? We are in a new paradigm where Adam Smith’s Invisible Hand is tied behind his back and other forces are in control. China’s technological momentum in strategic sectors such as batteries, green tech, AI, etc. is not a secret and Xi shows scant interest in having his legacy hemmed in by a Trump Administration still finding its footing around trade and economic policy with the use of tariffs and weaponization of the US Dollar. While these tactics will cause some near-term indigestion in the Chinese economy, one can’t help but assume that Trump’s remaking of the global trading system around an “America First” agenda will serve to accelerate Chinese competition in sectors critical to national and economic defense. This may happen without any participation on the part of the United States.  The Biden Administration’s “small yard, high fence” approach to slowing Chinese access to critical technologies may have slowed the Chinese ascent, but the Trump Administration’s purely transactional approach (semiconductor chips for permanent magnets) acknowledges the possibility that in this era of technological development, China may be delayed but not denied.

The shrinking of the manufacturing base in the United States took decades and was exacerbated by the lure of laissez faire free trade across borders, regardless of differences in political systems. Interestingly, the manufacturing workforce is still roughly 12.6 million people, down from 19.5 million at its peak in 1979. It may be decades before any significant manufacturing capacity comes back to the United States, so perhaps a reality check is in order around what can be accomplished.

This all starts with policy certainty in the US. Clarity, once and for all, around tariff levels is a starting point. No CEO can make a significant capital spending decision unless he or she knows their cost structure within a narrow band. A 160% tariff on anode imports may keep Chinese material out of the United States but isn’t likely to accelerate anode production onshore quickly enough to mitigate higher prices throughout the supply chain.

One path to competing is taking the “China model” of welcoming Chinese intellectual property onshore in the US. While the political class inside the Beltway in Washington DC won’t like this, this model (think Ford and CATL in Michigan) offers the path of least resistance to accelerating electrification in while keeping costs in check.

What this speaks to more broadly, is re-engagement with allies through partnerships – another current politically unpopular choice. 15 years analyzing global supply chains has taught me a great deal, but nothing more obvious than nobody – company or country – can do this alone. This is why the recent ICE raid on the Hyundai EV plant in Georgia is so disquieting. Our South Korean partners who were lending their technical expertise were led away in chains for all the world to see. The Chinese must be absolutely dumbfounded by their good fortune sure to result from this misstep.

Other tools to compete are already in play, though they are hanging by a thread in the current political environment. They include subsidies, tax breaks, off-takes and low interest loans. These are a sine qua non to move forward. All energy is subsidized in one form or another and the sooner we come to grips with this, the better. Is a $2.3B USD loan to Lithium Americas (LAC:NYSE) to help the company achieve commercial production and promote self-sufficiency and domestic production of a critical mineral a bad thing? Of course not. Especially when compared with some of the unconventional moves by the Trump Administration including taking equity stakes in companies such as Intel. How exactly does this investment help the company achieve its goals in the same way a loan to LAC has the potential to? We are going to find out if State Capitalism is a superior model to the traditional free market. I’m not optimistic.

CONCLUSION

In some ways, it’s interesting to note how little has changed since I wrote my initial piece in 2023. At that time, conventional wisdom centered around the idea that a robust industrial policy designed to slow China’s ascent and help the US get in a position to compete on the global stage would be straightforward. Taxpayer-subsidized reindustrialization was the new mantra. Runaway inflation and mistrust of the Biden Administration owing to perceived cognitive decline changed that calculus and re-elected Donald Trump. Now, everything from the US Dollar to industrial policy is a weapon. This is a theme that Foreign Affairs has devoted a great deal of ink to in recent months. The Trump Administration’s dismantling of the IRA will leave many wondering what could have been, and the America First agenda, underpinned by tariffs, and a lack of clarity on policy has sown confusion in board rooms and across borders which has yet to be resolved. This reindustrialization narrative was not going to be resolved within a single Presidential administration, so while the main roadblocks to growth in 2023 are still in place, we will be using a new set of State-led tools to compete.

Both the Biden and Trump Administrations have demonstrated the will to compete and reindustrialize. Trump’s “all of the above” energy supply-led approach (deregulation, domestic production, tariffs, fossil fuels) stands in contrast to Biden’s demand-led approach (consumer subsidies, renewables, ESG) but neither approach answers the question on which approach is better or more politically palatable.

In the past two years, the entire electrification narrative in the West has been reset. While metals demand looks strong through the end of the decade, EV uptake will be significantly lower, owing to the stubbornly high price of EVs and lost subsidies. Whether or not this air pocket of demand is filled by BESS demand remains to be seen.

The reindustrialization narrative has been reframed as a hybrid of national security and economic security. Tariffs and export controls are likely to drive up costs and stymie the flow of goods until a new form of global trade emerges.  This is a long game, and we aren’t any closer to determining a winner. Until these macro issues around economic policy, immigration, and access to technology are better understood, the shining city on a hill remains a distant beacon on the horizon.

  • Full Disclosure: I currently hold a long position in Lithium Americas (LAC:NYSE).

The Lithium-Ion Supply Chain View From North America - Shining City on a Hill or Fading Giant?

Chris BerryComment

Recently, I was invited to write an essay for a journal on the opportunities and challenges that North America faces as the buildout of lithium-ion supply chains intensifies.

After submitting the piece, I was informed that it was rejected. In the interest of openness and in hopes of stimulating conversation, I am publishing the original piece here (with only minor editing to account for recent events with the labor unions in the United States). I welcome any and all feedback.

The Lithium-Ion Supply Chain View from North America


Shining City on a Hill or Fading Giant?

By Chris Berry


In President Ronald Reagan’s Farewell Address, he referred to a vision of the United States as a “shining city on a hill” [i]. As North America embarks on a Green Industrial Revolution, the reference from the 40th President of the United States is apt in that North America (and much of the world) is at a crossroads. This crossroads is marked by both geopolitical (a new Cold War, rising authoritarianism, resource nationalism) and environmental (climate change) tensions, but how North America responds may determine the balance of geopolitical power for decades to come.

The decarbonization of industry is a multi-trillion-dollar challenge on a global scale which won’t be solved by either the private or public sector alone. Success means technological leadership, stable economic growth, productivity, job creation, and a cleaner environment for future generations.

Winning this race (supposing one can actually define what winning means) requires confronting several challenges – all of which can be overcome with a combination of capital, political will, and time. There are four primary challenges:

·      catching up to China’s lead in battery supply chain development and production

·      decoupling critical supply chains

·      increasing pricing and operational transparency along battery supply chains

·      balancing domestic priorities such as negotiating with labor unions

This is an incomplete list of challenges, but all must be faced to set a course for growth able to withstand volatile global economic environments.


CATCH ME IF YOU CAN

Perhaps the biggest challenge facing North America as it aims to develop next generation battery supply chains is catching up to China. Forty years of increasingly globalized trade, where the lowest cost of production was relentlessly pursued and declining interest rates manifested as cheap capital, is over. In its place is a mirror opposite – protectionism, a focus on reshoring of supply chains, and higher interest rates. All are recent phenomena unfamiliar to many policymakers, business owners, and financiers today. This domestic focus on industrialization is designed to counter China’s multi-decade economic policy of “capitalism with Chinese characteristics” – state-sponsored industrial capacity expansion underpinned by theft of western technology. China’s mercantilist economic model has produced an almost-insurmountable lead in various economic sectors including the lithium-ion battery supply chain, where dominance across mining, refining, cathode and anode production, cell and pack production, and recycling has been hiding in plain sight for years. If it weren’t for President Trump’s trade war and the supply chain paralysis resulting from COVID, private sector companies in western markets may not have ever addressed these issues harming North American economic competitiveness. 

Since President Joe Biden entered office in 2020, the solution to turbocharge US economic competitiveness has been to spend capital igniting a resurgence in industrial policy not seen since World War II. In the United States, both the Infrastructure Investment and Jobs Act (IIJA) in 2021[ii] and the Inflation Reduction Act (IRA) of 2022[iii] are designed to use carrots rather than sticks in the form of production and investment tax credits to incentivize domestic manufacturing of a host of green technologies including batteries. The IRA is a 730-page document which almost overnight has transformed the economics of lithium-ion battery production to the point where even US allies such as South Korea and the European Union are clutching their pearls and issuing pointed statements about the unfairness of new US industrial policy.[iv] As an example, Section 45X of the IRA offers a USD $45 per KWh tax credit for lithium-ion batteries produced in the United States. Though there is only a ten-year window to take advantage of this credit and the positive economics are undeniable, as the proverb says, “the road to hell is paved with good intentions” and an unintended consequence of the legislation may be a subsidy war, where companies hold out on investing until enormous subsidies are lavished on them. Case in point is the automaker Stellantis who halted construction of a gigafactory based in Canada until the Trudeau government and the province of Ontario came forward with billions more Loonies of financial support, lest the company move its operations to the US.[v]  

While the argument over just what is the right level of subsidy to grow a business is fodder for another piece, the fact remains that the Biden Administration has thrown down the battery gauntlet in an attempt to catch up with a well-developed Chinese battery supply chain. Though the IRA doesn’t directly address more domestically mined supply of battery raw materials, mining companies seem particularly well-positioned. The competition and (non-Chinese) cooperation amongst allies this inspires will be the catalysts for lower costs in the long run through economies of scale and leveraging of technologies, though we may see a higher industry cost structure in the near-term given the time needed to achieve true scale.


CONSCIOUS DECOUPLING

The motive behind the legislative onslaught described above is the perceived need to decouple critical supply chains from China. The need was first laid bare during the early stages of President Trump’s trade war and was exacerbated during COVID when we all found out just how inflexible many globalized supply chains really were. Since then, and despite the table pounding in Washington, there seems to be a divergence of opinion between the public and private sectors with respect to China and decoupling. While dislike of China and its mercantilist business practices seems to be the only thing Republicans and Democrats agree on in Washington DC in 2023, the private sector, highlighted by automotive companies, seems to be singing from a different hymnal. Case in point is Ford Motor Co and their partnership with CATL, based in China, the largest lithium-ion battery manufacturer on Earth. While the goal of the partnership is to build battery capacity in the state of Michigan with Ford owning the infrastructure and making hiring decisions and CATL essentially providing technical assistance with battery production, the deal has invited a rather pointed request for more details from US Congressmen Gallagher and Smith, Chairman of the Select Committee on China and Chairman of the Committee on Ways and Means respectively.[vi] Is this deal between Ford and CATL a subtle admission that Ford needs Chinese battery technology to compete? Is company management tone deaf to the ultimate goals of legislation such as the IRA or the CHIPS Act? These are questions that will be answered more clearly as we lurch towards a presidential election in the US in 2024 and China remains a convenient villain. Interestingly enough, the deal was recently “paused” by Ford due to the economics of the plant. While the real reason for this pause in construction remains to be seen, the fact is that Chinese battery technology will remain vital to Western OEM ambitions.

If domestic OEMs really do need Chinese battery technology to survive, how do we work more closely with allies in other countries such as South Korea or Japan that are already taking full advantage of the financial benefits of building battery infrastructure in North America? We will have an answer here, but it will be measured in years, rather than in shorter and politically convenient election cycles. A longer-term view of policy goals and objectives is perhaps more important than any specific subsection of any legislation. The economic justification for decoupling and the policy justification for decoupling may be different.   


PEERING THROUGH THE HAZE

Any supply chain rebuild cannot rely on federal funds alone to succeed. The private sector must participate. Historically, this has not happened widely due to the poor economics of building and operating manufacturing infrastructure in North America relative to Asia – a consequence of Globalization. The third challenge in North America involves building a supply chain that provides visibility and liquidity for financial markets participants. Lithium has historically been characterized as an oligopoly with a murky pricing structure at best. Ask five people what the price of lithium is, and you’ll receive five different answers, if that. While the China-based spot price accounts for a smaller portion of overall lithium traded volume, the roller coaster-like volatility of the spot price for lithium carbonate from $6,500 USD per tonne in late 2020 to a peak of $85,000 USD per tonne in late 2022 to the current level of $26,000 USD per tonne serves as an impediment to the enormous investment needed to build a lithium supply chain. Private capital is attracted to high returns and transparent pricing environments.

Given the focus on acquiring raw materials needed to achieve decarbonization goals, an unintended consequence may be increased pricing volatility as multiple companies and countries are now after a finite amount of available material. The implication here is that large pools of capital may sit on the sidelines or scan the investment horizon for opportunities downstream in the battery supply chain or in other technologies where a more appealing risk/reward ratio appears.

Fortunately, there are solutions in the works here with the London Metal Exchange, Chicago Mercantile Exchange, and the Guangzhou Futures Exchange offering futures contracts on specific types of lithium and cobalt with the goal of hedging against price volatility and protecting margins. While the liquidity in the futures contracts continues to build, this, coupled with more flexible and longer-term lithium off-take contracts between producers and end users, are keys to aid in sustainable growth of a regionalized battery industry. We have come a long way in a short period of time, however, more volume is needed across select battery metals markets to provide liquidity for financiers such as larger markets including nickel or copper.  


KEEPING YOUR (ECONOMIC) HOUSE IN ORDER

A fourth and final challenge involves balancing domestic priorities while competing on a global stage. The costs of climate change are becoming clearer given recent examples of heat waves, wildfires, and floods both locally and globally. The cost of the IRA of just shy of USD $400 billion for clean energy investment coupled with a similar amount of capital available from the Department of Energy’s Loan Programs Office is designed to mitigate the effects of climate change through massive green infrastructure investments. These costs (both explicit and implicit) aren’t likely to abate, despite the presumed long-term economic benefits of the IRA and IIJA investments in North America and so devoting public and private capital on an accelerated basis is crucial.

According to the Center for Automotive Research, the United States has seen announced investment in EV and battery infrastructure of $112 billion since 2018[vii] and we are likely to see much more as the benefits of the IRA make themselves felt. However, for all of the bullishness and momentum on EV sales light duty EV sales are still a cost center for major OEMs with Ford recently forecasting an EBIT loss in their EV business of USD $4.5 billion for 2023 – up from USD $3 billion forecast in the previous quarter.[viii] Traditional ICE sales are stemming losses for now, but more ICE sales only delays the transition to EVs and doesn’t help corporate America compete with runaway Chinese EV sales and supply chain dominance. As if that weren’t enough, major North American auto manufacturers are facing a looming domestic issue in labor contract negotiations with the United Auto Workers. EVs require fewer parts relative to their ICE cousins and therefore require less labor to build. While union officials know this, they are not willing to accept lower pay, especially as auto executives reap in million dollar salaries and the overall health of the Big Three North American auto manufacturers is robust with billions of dollars in profits thanks to sales of ICE cars. With the current contract with the UAW having expired on September 14, this thorny issue will be dealt with shortly with an uncertain outcome.


CONCLUSION

Nobody claimed that the energy transition would be easy, fast, or economical in the short term. Despite the macroeconomic challenges faced by North American companies in this transition highlighted by higher interest rates, the momentum towards a more electrified society appears unstoppable. The US and Canadian governments have been more than generous in incentivizing companies and “friendly” countries to build battery supply chain capacity domestically. The economic opportunity is almost too good to ignore despite the lack of affordability of many EVs currently. A revamped green industrial policy is sure to inject volatility into commodity prices as friend and foe alike all look to access a finite amount of multiple critical materials, however this is the price to be paid to build infrastructure, create jobs, and provide a cleaner climate for future generations. Building these supply chains will require creative decisions in board rooms across North America. The success of these decisions will ultimately determine whether or not North America remains the “shining city on a hill” referenced earlier or is left behind by countries that moved faster.


[i] https://www.reaganfoundation.org/media/128652/farewell.pdf

[ii] https://www.whitehouse.gov/briefing-room/statements-releases/2021/11/06/fact-sheet-the-bipartisan-infrastructure-deal/

[iii] https://www.whitehouse.gov/briefing-room/statements-releases/2022/08/19/fact-sheet-the-inflation-reduction-act-supports-workers-and-families/#:~:text=The%20Inflation%20Reduction%20Act%20will%20raise%20revenue%20by%3A,minimum%20corporate%20tax%20of%2015%25.

[iv] https://www.europarl.europa.eu/doceo/document/CRE-9-2022-12-14-ITM-004_EN.html

[v] https://www.reuters.com/business/autos-transportation/stellantis-says-resume-battery-plant-construction-canada-after-reaching-deal-2023-07-05/

[vi] https://www.politico.com/news/2023/07/21/house-gop-pair-launch-investigation-into-ford-battery-deal-00107597

[vii]https://www.wsj.com/articles/uaw-says-costly-ev-transition-wont-change-unions-demands-1561a725

[viii] https://www.cnn.com/2023/07/27/business/ford-earnings/index.html


A Few Thoughts On A Volatile 2022 for Battery Metals And A View to 2023

Chris BerryComment

What follows is a general listing of takeaways from recent conferences I attended both here in the US and in Europe in 2022. Some of these may seem obvious, but I wanted to include them here as there are ideas that have more momentum behind them than I initially thought (like reshoring.


·      The three most talked-about topics I encountered were:

o   Raw material pricing and inflation along the supply chain

o   The outsized role of China in overall EV demand and the general economic outlook for the country

o   How different technologies will affect the supply and demand balance of battery raw materials in the future. Examples include recycling, anode technology, and cathode blending

·      Reshoring of supply chains has enormous momentum behind it

o   Much of this has been turbocharged by the signing into law of the Inflation Reduction Act in the US

o   Every supply chain participant I surveyed throughout the year (auto OEMs, battery component producers, miners – close to two dozen) were actively planning on building a more localized supply chain infrastructure

o   There was widespread agreement that this will take years to materialize and is driven more by geopolitical concerns than cost (it’s hard to see how costs won’t increase as this infrastructure is built and operated)

·      The Inflation Reduction Act (IRA) entered into every conversation in both the US and Europe

o   There is a gigantic lack of clarity around how the law will be implemented (the eligibility for the EV tax credits is a major issue) and by when

o    It appears that the IRA will benefit the downstream portion of the supply chain (refining, cathode/anode production/cell and pack manufacturing/recycling)

·      The fatal flaw in the IRA is that it does not directly address mine permitting reform. As such the US will remain reliant on foreign allies (and some adversaries) for battery raw materials

o   The Department of the Treasury won’t issue guidance on the IRA before Q1 2023 – a slight delay owing to the enormous economic impacts to all involved

·      Traceability has the auto OEMs and battery manufacturers worried

o   As most Western auto OEMs do not have a vertically integrated EV strategy, the ability to trace a battery throughout its entire life has become very important (and exceedingly difficult) as battery manufacturer and EV manufacturer are often different entities

·      Auto OEMs I speak with would generally prefer to see batteries go through a second life use rather than recycling

o   This was a surprise to me as I think second life is much more manual and more of a hassle relative to recycling (which has its own set of challenges)

o   Cathode producers disagreed and were more in favor of recycling scrap and producing CAM and pCAM

·      Western OEMs announced that they are “fully supplied” with respect to batteries to 2025

o   This is new in that these same OEMs historically hadn’t been willing to make these claims. Color me skeptical given that many product offtake agreements are non-binding and with mining companies that either have no production experience or are not currently in commercial production

o   This also begs the question about what happens after 2025 given the decade of lead time needed to bring greenfield mine supply to market and get it qualified for automotive battery use

o   GM has announced a goal to secure 75% of their battery raw materials from the US by 2030. I think this is unlikely unless they plan on producing a miniscule number of EVs.

·      Inflation throughout the battery supply chain feels stickier than many would like

o   BNEF announced that lithium-ion battery pack pricing has flatlined at ~ $151/KWh (up 7% YoY) and this is due mainly to high raw materials and input pricing

o   Another longer-term concern is adequate expertise and labor along the supply chain (recycling, for example)

·      There was a sense that Chinese companies will still have a presence in the North American EV market despite the IRA rules around “foreign entity of concern”

o   All eyes are on potential tie ups between Ford and CATL and VinFast and Gotion to see how they thread the needle here

Happy to discuss any of this in more detail, so please do reach out.

The Wall of Worry in Battery Metals

Chris BerryComment

October 11, 2021

For a PDF version of this note, please click here.

Should investors be focusing on cost inflation along the supply chain rather stretched valuations?

With some lithium prices up over 200% in 2021, is it time to start to worry about an overextended run? Lithium pricing as per Benchmark Mineral Intelligence is at an all-time high on a nominal basis. The last time lithium prices were this high (2018), the adage of “taking the stairway up and the elevator down” became all too real and reminded us of just how violently cyclical and unforgiving dynamic markets such as lithium can be.

Lithium Panel Webinar with 121 Group

Chris BerryComment

I was pleased to participate in this investment panel (link here) which focuses on current lithium market dynamics including:

  1. Supply, demand, and pricing

  2. Macro dynamics of the current market

  3. Sustainability and low carbon lithium

  4. M&A

  5. Competing battery tech

About an hour long, but indexed so you can jump across different discussion topics.

The Evolution of the Revolution - The Path to Resilience and Keys to Battery Metals Growth

Chris BerryComment

By all accounts, we have been through an eventful four years with the boom, bust, and recent boom again in the battery metals. While it is important to remember that it’s never “different this time”, I do think we are at an interesting hinge in the electrification thesis. This hinge is notable in several ways as the battery metals markets mature and only increase in their strategic importance.

The market consensus for just about any battery metal calls for steadily increasing demand with a supply response that is likely to keep pace only in fits and starts, creating opportunities and threats for an investor base that is growing as the battery metals opportunity continues to make itself all but obvious.

In my previous article, I focused on the “state of play” for different battery metals, calling that moment in time Churchillian and viewing it as the “end of the beginning”.  While the general availability of the metals is important, this piece will focus more on the macro factors driving the current rally in the sector. I like to think of these forces as pillars underpinning this secular change in terms of how energy is generated, stored, and used. They can be thought of as the Four Ds: decarbonization, cost deflation, decoupling, and demand. However, it is the rise of geopolitical tensions and ESG that deserve a deeper discussion here. These forces will continue to play an increasingly important role in capital accumulation and allocation well into the future and I think require a reassessment of one’s investment rationale and philosophy.

CHESS OR CHECKERS? WHAT GAME ARE WE PLAYING?

Geopolitics and the associated tensions are set to play an increasingly central role in the global race to build electrification supply chains. This is one of the biggest changes in the landscape between previous cycles in battery metals and today. The line between economic security and national security has been blurred – perhaps permanently. One could argue that this line of thinking has steered China’s growth ambitions in recent decades, and it appears that other large trading blocs such as North America and the EU are set to follow suit, especially when you look at the trillions of dollars and euros of proposed stimulus directed towards “green growth”. 

An increasingly assertive China has to date flexed its muscles mainly through its checkbook, encouraging outward-bound economic development through the Belt and Road initiative (BRI) and internal growth through strategies such as Made in China 2025. Much of the capital invested in lithium development in recent years has come from China in the form of equity, debt, or off take and this current and future supply has been locked up. Concerns around debt trap diplomacy have served to halt some of the initial progress made in the early days of the BRI rollout, but with respect to battery metals supply chains, China is well ahead of the rest of the world.

The pendulum has clearly swung away from a more globalized “flat” trading system and it appears that a Biden Administration will not change course from the previous Administration’s approach to China. The meeting the US and China recently had in Alaska did not go as well as either side wanted and so more of the same tension is to be expected. The isolation of China or surrounding of the country by democracies (which I think is the point of the Quad – Australia, Japan, India, and the US) is a theme to watch closely but is also an opportunity for countries around the world to exploit their advantages as a top tier low-cost supplier of critical materials such as lithium or nickel.

So, if a rising China is less willing to play by global norms, this raises an important question being debated in corporate boardrooms and political capitols alike – is decoupling or regionalization of supply chains the next logical step here? An interesting side effect of COVID is the focus on selective decoupling of supply chains and the general push back against Chinese dominance of battery metals. With the EU pushing forward with its own EV supply chain through planned the spending of trillions of Euros, North America is no longer just competing with China for capital and market share. This is another incredibly important development in battery metals since 2017. Separate supply chains for certain industries such as PPE, or critical metals are a real possibility over the next decade. Capital is widely available due to low interest rates and accommodative central banks and (rare) political will is in place, but the patience to see this through is the only outstanding issue. The competition for raw materials, intellectual property, and intellectual capital is now a three-way race between the three largest economic blocs in the world: China, North America, and the EU. What does this mean for raw material availability?

 A LITTLE AIN’T ENOUGH (WITH APOLOGIES TO DAVID LEE ROTH)

Given the geopolitical backdrop, it has been encouraging to see the amount of capital raised in the lithium sector and recent M&A activity. Recent equity raises by Albemarle and SQM of over US $1 billion each combined with other equity capital raised in recent months put the total at over US $4 billion. For an industry that boasts global revenues currently well below that, this is a significant accomplishment and testament to the belief in future growth on the part of companies and investors. Additionally, the US $3.1 billion merger between Orocobre and Galaxy Lithium helps to consolidate the lithium producer sector while building a new market participant with both geographic and geologic diversity and a strong balance sheet. Incidentally, the strategy of growth via M&A has a history of success in lithium judging by the outcomes of the Lithium Americas-Western Lithium merger and the take over of Altura Mining by Pilbara Minerals. Though much more capital is needed, there may be a lesson in here for battery metals companies thinking about balance sheet sustainability throughout this decade.

Seasoned battery metals investors have debated the potential for a structural shortage of material which will underpin any shift towards electrification since early in the last decade. This is an important but nuanced argument and really must be thought through on a raw material-specific basis. While the trajectory for lithium or copper is clear, the electrification thesis will affect these markets differently give their overall sizes, dependence on battery growth, and pricing transparency. Given the vagaries in pricing and associated volatility, perhaps a strategy of just locking up raw material supply is no longer enough. I would argue that owning the intellectual property around resource extraction (such as direct lithium extraction technology), cathode and anode production, or battery recycling is at least as important going forward. There is no shortage of any battery metal “in the ground”. Certain battery metals contain known resources that would last decades even at current elevated consumption rates. The real challenge is in producing battery grade material at scale and the battery metals producers have historically found this a challenging endeavor, so a focus on more efficient extraction and production methods offers somewhat of a hedge to these challenges as supply chain infrastructure is built out.

ESG IS THE VIP

Finally, once we have established the “why” for building battery metals supply chains, the “how” will become increasingly important. This speaks to the newfound emphasis on ESG goals across the industry.  Turbocharged growth, opaque pricing dynamics and oligopolistic market structures have left battery metals development to a relatively few companies and a few countries. For the industry to grow to meet surging demand to serve the EV and renewables markets, the origin and flow of materials such as lithium or rare earth elements must become much more transparent while also keeping a lid on costs. Ironically, a more transparent supply chain likely involves increased domestic mining capacity and should be a priority in global capitals such as Washington DC, Ottawa, or Brussels. This may drive up costs but is a worthy price to pay for supply chain transparency and self-sufficiency. We know we are going to need more raw materials to achieve aggressive decarbonization goals. Would you rather the raw materials come from countries where ESG criteria are more difficult to monitor? This is a key question facing all stakeholders involved with the decarbonization thesis.  

Capital is the fuel that breathes life into the energy metals sector and is the bridge between ore in the ground and the battery in your car. With a more relentless focus on projects that adhere to a strict ESG criteria those projects that can demonstrate a strict adherence should be first in line for “green” funding. Capital always finds a home where it is treated well and jurisdictions with an attractive investment profile, proximity to major end markets, and respect for the rule of law would appear to be a prime destination for some of the capital needed to construct resilient battery metals supply chains. It is incumbent upon both the public and private sector to coordinate efforts to raise and deploy capital in an efficient and effective manner.

PIECING IT ALL TOGETHER

The bottom line here is that to hit even modest electrification goals (10%, for example) we are going to need an enormous amount more material and these typically small markets such as lithium or rare earth elements will need to scale flawlessly and aggressively – no easy feat when you consider the fact that these are really specialty chemicals that are being produced. New supply will have to come from existing players, new players, recycling, and a leveraging of technology. This is necessitated by the factors discussed earlier in geopolitics, supply chains, and ESG. While the demand appears to be there, a coordinated effort between the public and private sectors which focuses on R&D and project development is the optimal way to ensure supply from domestic sources or other allies.

The bullish narrative around battery metals has been amazingly resilient and accelerated somewhat because of the effect of COVID on supply chains. This perceived freight train of demand is about to run headlong into several industry-wide challenges including increasing product purity demands, decarbonization/ESG requirements, and a potentially inflationary supply chain rebuild. A key takeaway is cost curves for battery metals including lithium and cobalt will almost certainly have to rise, implying a positive outlook for battery chemicals producers that can finance, build capacity, and sell product to a growing list of downstream customers. 

In the 20th Century, owning the raw materials in a supply chain conferred a competitive advantage. Just ask Henry Ford. However, the 21st Century demands something more as raw material control is not enough. Developing and owning the intellectual property around battery metals supply chains is the next Great Game. A holistic view of each piece of the supply chain and technology’s effects on it offers a front row seat to the opportunities and challenges that will confront investors as we move on from the “end of the beginning” over the next decade.

Taming The Hydra: Funding The Lithium Ion Supply Chain in an Era of Unprecedented Volatility

Chris BerryComment

Earlier this year, I was asked to contribute a chapter to a forthcoming textbook on Lithium Storage. I jumped at the chance here as much of the academic literature on the lithium business is a little dry, to say the least.

The focus of the chapter is on financing challenges for the lithium supply chain as the overall growth continues in fits and starts. Rather than a “how to” manual, this chapter takes a case study approach. Here is the link:

https://www.intechopen.com/online-first/taming-the-hydra-funding-the-lithium-ion-supply-chain-in-an-era-of-unprecedented-volatility

Click here for a pdf copy and comments welcome!